

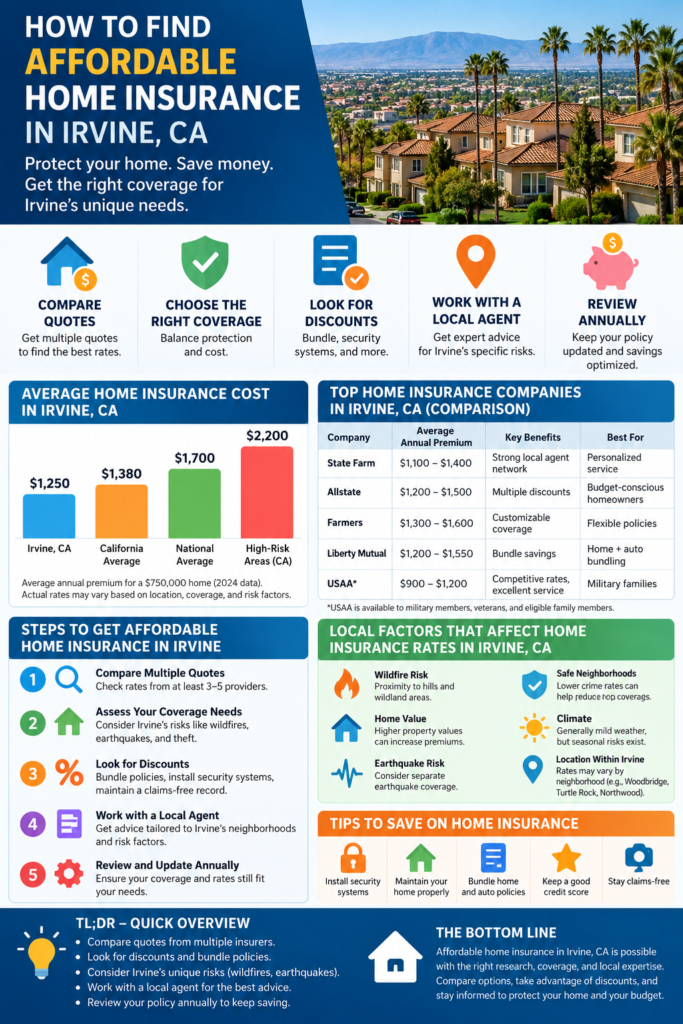

How to Find Affordable Home Insurance in Irvine, CA: 9 Smart Ways to Save
Finding affordable home insurance in Irvine, CA, does not mean you have to sacrifice the protection your home and belongings need. Whether you own a single-family home in Woodbridge, a property in Northwood, a house in Turtle Rock, or a home near the Irvine Spectrum area, comparing insurance options can help you find coverage that fits your property, budget, and financial goals.
Home insurance costs can vary significantly depending on your home’s rebuilding cost, age, roof condition, claims history, coverage limits, deductible, and the insurer’s underwriting guidelines. California’s changing homeowners insurance market makes it especially important to understand what you are buying before accepting a quote.
This guide explains how to compare home insurance in Irvine, identify potential savings, understand coverage differences, and choose a policy based on value rather than price alone.
Quick Overview: Affordable Home Insurance in Irvine, CA
Affordable home insurance in Irvine, CA, starts with comparing multiple quotes for similar coverage. Review dwelling coverage, personal property protection, liability limits, deductibles, exclusions, and available discounts. You may be able to reduce your premium by bundling policies, improving home security, reviewing your deductible, and keeping your property information accurate. Always confirm that the policy provides enough coverage to rebuild your home after a covered loss.
TL;DR: How to Find Cheap Home Insurance in Irvine
To find affordable homeowners insurance in Irvine, compare quotes from multiple insurers, check California Department of Insurance comparison tools, and make sure each quote uses similar coverage limits. Ask about home and auto bundling, security discounts, roof-related eligibility, and other available savings. Choose a deductible you can comfortably afford, avoid underinsuring your home, and read policy exclusions carefully. If traditional coverage is difficult to obtain, explore additional options with a licensed insurance professional before considering the California FAIR Plan.
Key Takeaways
- Compare multiple homeowners insurance quotes before choosing a policy.
- Use the same coverage limits and deductibles when comparing prices.
- Calculate dwelling coverage based on estimated rebuilding cost, not simply the home’s market value.
- Ask insurers about bundling, security systems, and other available discounts.
- Review roof condition, plumbing, electrical systems, and property maintenance.
- Understand wildfire exclusions, water damage limitations, deductibles, and other policy conditions.
- Consider liability protection and personal property coverage alongside the dwelling limit.
- Use official California insurance comparison resources to research rates and coverage.
- Request a personalized quote to determine which options are available for your specific Irvine property.
Table of Contents
Why Affordable Home Insurance Matters in Irvine, CA
Irvine is a popular Orange County community with a wide variety of residential properties, from condominiums and townhomes to larger detached houses. Protecting these properties requires more than finding the lowest advertised insurance price.
A homeowners insurance policy may help pay for covered damage to your home, replace eligible personal belongings, provide personal liability protection, and cover additional living expenses when a covered loss makes your home temporarily uninhabitable. The exact protection depends on the policy’s terms, limits, exclusions, and endorsements.
For many Irvine homeowners, the challenge is finding the right balance between monthly or annual premiums and meaningful financial protection.
A policy with a lower premium may have a higher deductible, lower limits, or exclusions that matter to your circumstances. A more expensive policy may offer broader protection, but higher pricing does not automatically mean better coverage.
The goal is to find a policy that provides appropriate protection at a price that works for your household.
What Affects Home Insurance Costs in Irvine, CA?
Insurance companies evaluate several details when determining whether they can insure a property and how much the policy may cost. Two houses in Irvine can receive different quotes even when they are in the same neighborhood.
| Pricing Factor | How It Can Affect Your Premium |
|---|---|
| Home rebuilding cost | A higher estimated cost to rebuild can increase the amount of dwelling coverage needed. |
| Home age and condition | Older plumbing, electrical systems, roofing, or other components may affect eligibility and pricing. |
| Roof condition | The roof’s age, materials, condition, and loss-prevention features may influence underwriting. |
| Location and property risk | Insurers may consider wildfire exposure, local hazards, emergency access, and other location-specific factors. |
| Claims history | Prior claims may influence eligibility or pricing, depending on the insurer’s rules and applicable law. |
| Deductible | A higher deductible may reduce the premium, but it increases the amount you pay for a covered claim. |
| Coverage limits | Higher dwelling, personal property, or liability limits can affect the total price. |
| Protective features | Eligible alarms, monitored security systems, and other protective measures may qualify for discounts. |
| Policy options | Water backup, earthquake coverage, and other optional protections can change the overall cost. |
These factors are not applied identically by every insurer. For that reason, the most reliable way to understand the cost of home insurance in Irvine is to request quotes using accurate information about your specific property.
9 Smart Ways to Find Affordable Home Insurance in Irvine, CA
1. Compare Quotes From Multiple Insurance Companies
One of the most effective ways to search for affordable home insurance is to compare more than one insurer.
Insurance companies have different underwriting guidelines, pricing structures, eligibility requirements, and coverage options. An insurer that offers a competitive price for one property may not offer the best option for another.
When comparing quotes, provide consistent information about your home’s square footage, construction type, roof, year built, updates, security features, and desired coverage. This makes it easier to identify meaningful price differences.
The California Department of Insurance premium comparison resources provide sample premium information for homeowners and other residential insurance products. These figures are useful for research, but they are not personalized quotes or guarantees of eligibility.
2. Ask About Bundling Home and Auto Insurance
If you already have car insurance, ask whether the same insurer offers a home and auto bundle.
Some companies provide a multi-policy discount when customers insure more than one eligible asset with them. However, bundling does not always produce the lowest combined price.
Compare the total cost of both policies against the cost of buying home and auto insurance separately. Check that the coverage remains appropriate on both policies.
A discount is only useful if the final price and coverage are competitive.
3. Choose a Deductible You Can Afford
Your deductible is the amount you generally pay toward a covered claim before the insurer pays the remaining covered amount, subject to policy terms.
A higher deductible may lower your premium. However, you need to be able to pay that amount if a covered loss occurs.
Before increasing your deductible, ask yourself whether you could comfortably cover the expense without borrowing money or using funds reserved for essential bills.
Also check whether the policy has separate deductibles for particular types of damage. A percentage-based deductible, where applicable, can be substantially different from a flat-dollar deductible.
4. Review Your Home’s Rebuilding Cost
Your home’s market value and rebuilding cost are not the same thing.
Market value includes factors such as the land, neighborhood demand, and local real estate conditions. Dwelling coverage is generally intended to address the cost of repairing or rebuilding the insured structure after a covered loss, subject to the policy’s terms and limits.
Construction labor, materials, architectural details, permits, and local building requirements can all affect rebuilding costs.
Ask your insurance professional how the dwelling limit was estimated. Make sure the information reflects your home’s size, features, construction quality, and any renovations.
Do not reduce dwelling coverage simply to obtain a cheaper premium without understanding the potential financial consequences.
5. Ask About Available Discounts
Discounts vary by insurer and property. Ask which discounts are available for your specific home rather than assuming every company offers the same savings.
Potential discounts or rating credits may relate to:
- Bundling eligible home and auto policies
- Monitored burglar or fire alarms
- Approved security systems
- Eligible roof or home improvements
- Claims-free history, where offered and permitted
- Other insurer-specific protective features
Confirm what documentation is required and whether a feature must meet particular installation or monitoring standards.
6. Maintain Your Roof, Plumbing, and Electrical Systems
Regular maintenance can help prevent avoidable damage and keep your home in better condition.
Inspect for roof deterioration, plumbing leaks, worn supply lines, electrical problems, and water intrusion. Address issues promptly and retain records of significant repairs or upgrades.
Home improvements do not guarantee a discount or policy approval. However, accurate maintenance records can help an insurer evaluate your property and may support eligibility with some companies.
Before starting a major renovation, ask whether the work could affect your insurance coverage or whether you need to notify the insurer.
7. Review Your Personal Property Coverage
Your homeowners policy may include coverage for belongings such as furniture, clothing, electronics, and household equipment. The applicable limit and settlement terms depend on your policy.
Walk through your home and consider the approximate cost of replacing your belongings. Create a home inventory with photographs, receipts, serial numbers, and descriptions of valuable items.
Check whether personal property coverage uses replacement cost or actual cash value. Actual cash value generally accounts for depreciation, while replacement-cost coverage may pay the cost to replace covered items subject to the policy’s conditions.
High-value jewelry, art, collectibles, and certain other possessions may require additional coverage or scheduling.
8. Check Liability Limits and Optional Coverages
Homeowners insurance can include personal liability protection for certain covered claims involving bodily injury or property damage for which you are legally responsible.
Review the liability limit and consider whether it fits your financial circumstances, household, and potential exposure.
You should also review additional living expenses, medical payments to others, water damage limitations, and exclusions. Flood and earthquake damage generally require separate consideration because standard homeowners policies commonly exclude these perils or do not provide the full protection a homeowner may expect.
Do not remove important coverage simply because the premium appears lower. First understand what you would be responsible for paying if the excluded event occurred.
9. Review Your Policy Every Year
Your home and financial circumstances can change from year to year. Renovations, new possessions, changes in rebuilding costs, or a new insurer’s underwriting rules can affect your insurance needs.
Review your renewal documents before the expiration date. Check the premium, dwelling limit, deductible, personal property coverage, liability limit, exclusions, and endorsements.
If the premium has increased, ask the insurer or your agent to explain the change. You can then compare alternative quotes using equivalent coverage.
Home Insurance Coverage Comparison: What Should You Look For?
When shopping for affordable homeowners insurance in Irvine, compare the coverage components rather than focusing on the annual premium alone.
| Coverage Type | What It Generally Helps Protect | What to Check |
|---|---|---|
| Dwelling coverage | The insured home’s structure against covered causes of loss. | Rebuilding estimate, limit, exclusions, and applicable replacement-cost provisions. |
| Other structures | Eligible detached structures such as a separate garage or fence. | Whether the limit is adequate for structures on your property. |
| Personal property | Eligible belongings inside or away from the home, subject to policy terms. | Coverage limit, sublimits, and replacement-cost versus actual-cash-value settlement. |
| Loss of use | Additional living expenses when a covered loss makes the home uninhabitable. | Limits, time restrictions, and covered circumstances. |
| Personal liability | Certain covered claims alleging bodily injury or property damage for which you are legally responsible. | Liability limits and exclusions. |
| Medical payments to others | Certain eligible minor medical expenses for guests, subject to policy terms. | Available limit and conditions. |
| Water backup or other endorsements | Specific additional risks when the relevant endorsement is available and purchased. | Covered causes, limits, deductibles, and exclusions. |
The policy contract determines the actual protection. Review the complete terms before buying or changing coverage.
For a side-by-side look at policy features, use the California Homeowners Coverage Comparison Tool. It can help you compare policy provisions, but it does not replace reviewing the actual policy offered to you.
How to Compare Home Insurance Quotes in Irvine, CA
Imagine an Irvine homeowner receives three quotes for the same property. The cheapest quote is not automatically the best option because the policies may have different limits, deductibles, exclusions, or optional coverage.
The following table shows how to organize a comparison. These are illustrative examples, not actual insurer quotes or market prices.
| Comparison Item | Quote A | Quote B | Quote C |
|---|---|---|---|
| Annual premium | $1,800 | $2,050 | $1,950 |
| Dwelling limit | $700,000 | $700,000 | $700,000 |
| Deductible | $5,000 | $2,500 | $5,000 |
| Personal property coverage | Review policy | Review policy | Review policy |
| Liability limit | Review policy | Review policy | Review policy |
| Important exclusions | Check wording | Check wording | Check wording |
In this illustration, Quote A has the lowest premium but a higher deductible than Quote B. Whether it is the better choice depends on the full coverage terms and the homeowner’s ability to pay the deductible.
Before deciding, request a written explanation of important differences. Compare the same dwelling limit, similar liability limits, equivalent deductibles, personal property settlement terms, and relevant endorsements.
Questions to Ask Before Buying
- Is the insurer willing to insure my specific Irvine property?
- How was the dwelling coverage limit calculated?
- What deductible applies to each type of covered loss?
- Are there special exclusions or restrictions involving water, roofs, or wildfire?
- Does the policy include replacement-cost coverage for personal belongings?
- Are additional living expenses covered, and what limits apply?
- Which discounts are included in the quote?
- Could my premium change at renewal?
- What steps should I take if the property is renovated or significantly improved?
How Much Home Insurance Do You Need in Irvine?
The right amount of homeowners insurance depends on the home, its contents, your financial circumstances, and the protection available under the policy.
Dwelling Coverage
Estimate the cost to rebuild the structure rather than using the home’s sale price or current market value as the only measure. Consider the home’s size, materials, construction quality, features, and local rebuilding expenses.
Personal Property Coverage
Make a household inventory and estimate the cost of replacing your belongings. Check special limits for valuable items and ask whether scheduled coverage is appropriate.
Personal Liability Coverage
Review your liability limit in light of your assets, household circumstances, and potential exposures. Homeowners with more substantial assets may also want to ask a licensed professional about umbrella liability insurance.
Learn more about additional liability protection through our insurance services.
Additional Living Expenses
If a covered loss makes your home temporarily uninhabitable, additional living expenses coverage may help pay eligible costs above your normal living expenses, subject to policy limits and conditions.
Do not assume that every event that damages a home triggers this coverage. The underlying cause of loss must be covered, and the policy’s terms apply.
Home Insurance Discounts Irvine Homeowners Should Ask About
Discounts differ among insurance companies, and not every discount is available to every property. Ask the insurer to identify the discounts for which your home may qualify.
| Potential Savings Option | What to Ask |
|---|---|
| Home and auto bundle | Would combining policies reduce the total cost compared with separate policies? |
| Monitored alarm system | Does the insurer offer a discount for a qualifying monitored security or fire alarm? |
| Roof improvements | Do roof age, material, or qualifying upgrades affect eligibility or pricing? |
| Protective devices | Are approved smoke detectors, water leak sensors, or other devices recognized? |
| Claims-free history | Is a discount available for an eligible claims history? |
| Other policy credits | Are there other credits based on the property’s features or policy combination? |
Before spending money on an upgrade for insurance savings, confirm that the insurer recognizes the improvement and explain what documentation is required. A home improvement can be worthwhile for safety or maintenance even when it does not result in a discount.
Finding Affordable Home Insurance in California’s Changing Market
Homeowners across California have faced challenges finding or renewing property insurance. Availability and pricing depend on the individual property, location, insurer appetite, and the risk characteristics an insurer evaluates.
For Irvine homeowners, the practical response is to start shopping early, keep property information current, and compare options before a renewal deadline.
Use California’s Home Insurance Comparison Tools
The California Department of Insurance offers tools that help consumers research residential insurance, compare sample premiums, review policy provisions, and find insurers or agents.
- California Department of Insurance: Home and Residential Insurance
- California Homeowners Insurance Comparison Tool
- California’s Top Ten Tips for Finding Residential Insurance
- California Residential Insurance Consumer Guide
Comparison tools use sample property profiles and may not include every discount, surcharge, or underwriting consideration. Treat their results as research rather than a binding offer for your home.
What If You Cannot Find a Standard Homeowners Policy?
If multiple insurers decline to offer coverage, ask a licensed insurance professional to explain the reason and identify other available options.
Depending on your circumstances, you may be able to explore additional insurers, alternative markets, or the California FAIR Plan. The FAIR Plan is intended as a last-resort option for eligible properties that cannot obtain coverage through the regular market.
Importantly, the California FAIR Plan is not equivalent to a comprehensive standard homeowners policy. Its core property coverage is limited, and homeowners may need separate coverage to address certain risks not included in the FAIR Plan policy.
Review the official California FAIR Plan information and ask about appropriate supplemental coverage before making a decision.
Home Insurance Considerations for Irvine Homeowners
Although homeowners in Irvine share a general local market, individual properties can have different insurance needs.
Single-Family Homes
Owners of detached houses should review dwelling coverage, other structures, roof condition, personal property, liability limits, and additional living expenses.
Townhomes and Condominiums
Condominium and townhome insurance needs depend on the property ownership structure and the homeowners association’s master policy. Confirm what the association insures and what remains your responsibility.
A condo policy may need to cover interior improvements, personal belongings, personal liability, and other exposures not fully covered by the association’s policy.
Homes With Recent Renovations
If you have upgraded a kitchen, remodeled bathrooms, added square footage, or installed higher-value finishes, make sure your insurance information reflects those changes.
Properties Near Higher-Risk Areas
Insurers may consider location-specific hazards, including wildfire exposure, when evaluating a property. Do not assume every Irvine neighborhood or property has the same risk rating.
If an insurer identifies wildfire exposure as a concern, ask what property-level mitigation measures may help and whether those measures affect eligibility or pricing. Any discount depends on the insurer’s rules and the characteristics of the property.
Rental and Investment Properties
If you rent out a home rather than occupy it as your primary residence, tell the insurer. A landlord or rental dwelling policy may be more appropriate than a standard owner-occupied homeowners policy.
5 Home Insurance Shopping Mistakes to Avoid
1. Choosing the Lowest Price Without Reading the Policy
A low premium may come with a larger deductible, lower limits, or exclusions that leave you with more financial responsibility after a loss.
2. Insuring the Home for Its Market Value
The cost to rebuild a home is different from the price at which it could sell. Base dwelling coverage on an appropriate rebuilding estimate.
3. Assuming Flood and Earthquake Damage Are Covered
Standard homeowners insurance generally does not provide comprehensive flood or earthquake protection. Ask about separate policies or endorsements that may be available for these risks.
4. Forgetting to Update Coverage After Renovations
Major improvements can change the cost to rebuild your home and replace its contents. Inform your insurer about significant changes.
5. Waiting Until the Last Minute to Shop
Start reviewing options well before your renewal date. If you receive a nonrenewal notice, begin looking for alternatives promptly rather than waiting until coverage is about to expire.
Why Consider California Insurance Quotes for Home Insurance in Irvine?
Finding suitable homeowners insurance can involve comparing coverage, understanding policy language, and determining which insurers may consider your property.
California Insurance Quotes provides insurance information and quote assistance for California individuals, families, and businesses. Through its connection with Julie Wong Insurance – TWFG, the website helps consumers explore insurance options based on their needs.
Personalized Quote Assistance
Your home, coverage requirements, and budget are unique. A personalized discussion can help identify the information needed to request and compare suitable options.
Coverage-Focused Comparisons
A useful comparison should consider more than price. Dwelling limits, deductibles, liability protection, personal property coverage, exclusions, and insurer eligibility all matter.
California Insurance Resources
Homeowners can use official California insurance resources alongside professional assistance to make informed decisions about coverage and availability.
Support for Different Insurance Needs
Homeowners may also need auto insurance, umbrella liability coverage, or other policies. Reviewing related insurance needs can help you understand potential policy combinations and whether bundling is worthwhile.
Explore our insurance services or visit the About California Insurance Quotes page to learn more.
Get an Affordable Home Insurance Quote for Your Irvine Property
Do not settle for a price without knowing what the policy actually covers. If you are buying a home in Irvine, reviewing a renewal increase, or comparing alternatives, take the time to explore your options.
Request a personalized home insurance quote and compare coverage based on your property, rebuilding needs, deductible preferences, and budget.
Request a Home Insurance Quote
Call 949-606-4778 or email jwong@twfg.com to discuss your insurance needs.
A quote comparison can help you understand the options available to you. Final premiums and eligibility depend on the insurer’s underwriting review and the details of your property.
Frequently Asked Questions About Affordable Home Insurance in Irvine, CA
How can I find affordable home insurance in Irvine, CA?
Compare quotes from multiple insurers, use similar coverage limits when comparing prices, ask about available discounts, review your deductible, and make sure your dwelling coverage reflects rebuilding costs. Compare exclusions and policy conditions before choosing a policy.
How much does homeowners insurance cost in Irvine?
There is no single price for every Irvine home. Premiums depend on the property, rebuilding estimate, roof condition, claims history, deductible, coverage limits, location-specific risk, and insurer underwriting. Request a personalized quote to determine your available options.
What is the cheapest home insurance company in Irvine, California?
No insurer is consistently the cheapest for every Irvine homeowner. The lowest-priced option depends on your property’s characteristics, coverage needs, and the insurer’s eligibility and pricing rules. Compare multiple quotes using equivalent coverage.
Does bundling home and auto insurance save money in Irvine?
It may. Some insurers offer multi-policy discounts, but bundling does not always produce the lowest combined price. Compare the total cost and coverage of bundled policies against separate policies.
What factors affect home insurance rates in Irvine?
Common factors include dwelling replacement cost, property condition, roof age, coverage limits, deductible, claims history, protective devices, and location-specific risks. Different insurers weigh these factors differently.
Is homeowners insurance required in California?
California generally does not require every homeowner by state law to buy a standard homeowners insurance policy. However, mortgage lenders commonly require property insurance as a condition of a home loan. Owners should understand the financial risks of going without appropriate coverage.
Does home insurance cover earthquakes in Irvine?
Standard homeowners insurance generally excludes earthquake damage. Separate earthquake insurance may be available. Review the coverage, deductible, limits, and exclusions before purchasing it.
Does home insurance cover flooding in Irvine?
Standard homeowners policies generally exclude flood damage. Separate flood insurance may be available through the National Flood Insurance Program or private insurers, depending on eligibility and location.
Can I lower my home insurance premium by increasing my deductible?
A higher deductible may lower the premium, depending on the insurer and policy. However, you would generally pay more out of pocket for a covered claim. Choose a deductible you can realistically afford.
What if I cannot find homeowners insurance in California?
Contact a licensed insurance professional to explore additional insurers and available markets. If standard coverage remains unavailable, you may consider the California FAIR Plan as a last-resort option. Because its coverage is limited, ask whether supplemental coverage is necessary.
Should I use the California Department of Insurance comparison tool?
Yes. The California Department of Insurance offers homeowners premium and coverage comparison resources. These tools can help with research, but sample prices are not personalized quotes and may not reflect every discount, surcharge, or underwriting decision.
How often should I review my home insurance policy?
Review your policy at least once a year and after major renovations, additions, significant purchases, or other changes that may affect rebuilding cost or coverage needs. Review any renewal increase before accepting the next policy term.
Helpful Home Insurance Resources
Use these resources to learn more about homeowners insurance, compare available policies, and understand California’s insurance market.
- California Insurance Quotes Home
- Explore Insurance Services
- Frequently Asked Insurance Questions
- About California Insurance Quotes
- California Department of Insurance: Home and Residential Insurance
- California Insurance Premium Comparison Tools
- Top Ten Tips for Finding Residential Insurance
- California FAIR Plan Information
Compare Home Insurance Options From Established Providers
When researching home insurance, you can also review information from established insurance companies to understand their product offerings and eligibility requirements. Availability varies by property and insurer, so do not assume every company will quote every Irvine home.
- State Farm Homeowners Insurance
- Allstate Home Insurance
- Farmers Home Insurance
- Progressive Homeowners Insurance
These links are provided for comparison and research. They do not indicate an endorsement or guarantee of coverage availability, price, or eligibility.
Home Insurance Terms Irvine Homeowners Should Know
| Term | Meaning |
|---|---|
| Premium | The amount charged for an insurance policy. |
| Deductible | The amount you generally pay toward a covered loss before the insurer pays the remaining covered amount, subject to policy terms. |
| Dwelling Coverage | Coverage for the insured home’s structure against covered causes of loss. |
| Replacement Cost | The estimated cost to replace or rebuild covered property without subtracting depreciation, subject to the policy’s terms and limits. |
| Actual Cash Value | A settlement method that generally accounts for depreciation. |
| Personal Liability | Coverage for certain claims alleging bodily injury or property damage for which an insured is legally responsible. |
| Endorsement | A policy addition or amendment that changes the coverage provided. |
| Exclusion | A policy provision describing a loss, cause, or circumstance that is not covered. |
| FAIR Plan | California’s last-resort property insurance option for eligible consumers who cannot obtain coverage through the regular market. |
Final Thoughts: Find the Right Home Insurance for Your Irvine Property
Finding affordable home insurance in Irvine, CA, starts with understanding what your property needs and comparing policies that offer similar protection.
Review rebuilding costs, deductibles, personal property limits, liability protection, optional coverage, and exclusions. Ask about available discounts, but do not assume the lowest premium offers the best overall value.
Use California Department of Insurance resources to research the market and compare coverage options. If you encounter difficulties obtaining insurance, begin exploring alternatives early and understand the limitations of any policy before purchasing it.
Ready to compare your options? Contact California Insurance Quotes to discuss your insurance needs and request a personalized quote for your circumstances.
Start your California insurance quote request or call 949-606-4778.